How Battery Gigafactories Choose Locations: Power, Customers and Subsidies
Mostly on electricity, customers and government money, with minerals further down the list than people expect. When you look at how battery gigafactories choose locations, the plants tend to go where power is cheap and reliable, where carmakers already build vehicles, and where a government is willing to share the cost.
That surprises people who assume a battery plant should sit next to a lithium mine. Raw materials matter, but they’re usually refined somewhere else first, and refined materials ship reasonably well. Finished cells and packs are heavy, bulky and classed as dangerous goods for transport, so being close to the assembly line is often worth more than being close to the mine.
How battery gigafactories choose locations, factor by factor
| Factor | Why it matters |
|---|---|
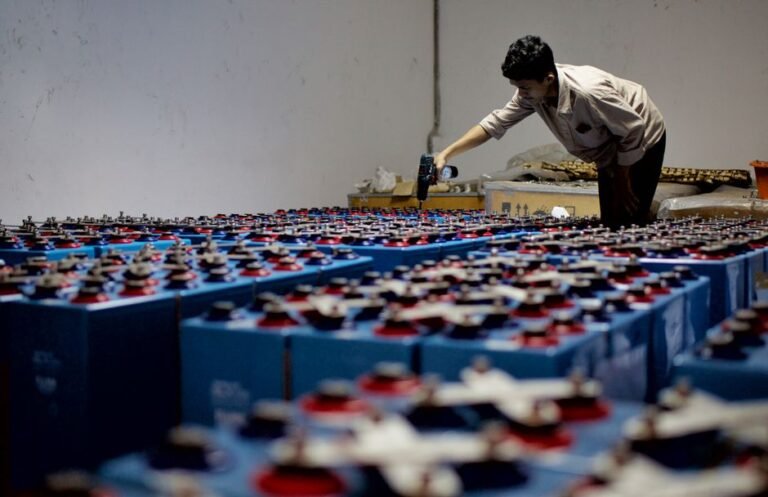
| Electricity | Cell making is energy-hungry: electrode drying, humidity-controlled dry rooms and formation charging all run constantly. Low-carbon power also lowers the emissions attached to every cell. |
| Nearby vehicle plants | Short trips to the customer cut freight cost and risk. Many plants are joint ventures with a single automaker for this reason. |
| Subsidies and trade rules | Grants, tax breaks and local-content requirements can change the maths of a site entirely. |
| Labor | Plants need thousands of workers, including technicians who can be trained for clean-room style production. |
| Land, water and permits | A single site can cover hundreds of acres and needs industrial water supply and a permitting process that won’t take years. |
| Supply chain | Cathode, anode and separator suppliers tend to cluster around cell plants, and vice versa. |
Electricity shows up in both cost and carbon. The emissions from making a pack depend heavily on the grid feeding the factory, which is one reason the same battery can carry a very different footprint depending on where it was built. We compare that against driving emissions in manufacturing versus use-phase emissions.
Why policy moves the map
The International Energy Agency’s report on batteries and secure energy transitions describes a supply chain heavily concentrated in China, which produces the large majority of the world’s cells. The US and Europe have used incentives and content rules to pull production closer to home, and those programs are the reason so many plant announcements clustered in particular regions over the past few years.
The catch is that policy changes faster than a factory can be built. Incentive programs have been revised or scaled back several times, and as of September 2026 some previously announced plants have been delayed, downsized or repurposed. A location that made sense under one set of rules can look shakier under the next.
Chemistry choices feed in too. A plant built for lithium iron phosphate cells has different supplier needs than one making nickel-rich cells, and shifts like the move toward cobalt-free batteries change which materials need to be nearby.
For a car buyer, none of this changes how a battery performs on the road. It does affect where vehicles get built, how exposed prices are to trade disputes, and how much of a car’s footprint was locked in before it left the factory. Treat any headline about a new plant as a plan, not a finished fact, until production starts.